2026 Car Financing Guide: How to Secure a Smarter Deal
Navigating 2026 car financing? Learn how to avoid record-high interest rates, manage monthly payments, and secure the best loan terms for your next vehicle.
There is a specific, quiet magic to the moment you pull a new car off the lot—the scent of fresh materials, the crisp response of a modern engine, and the promise of thousands of miles of open road ahead. Yet, for many American buyers in 2026, that sense of wonder is increasingly shadowed by the cold reality of the finance office. With the average amount financed for a new vehicle climbing to a record $44,664, understanding the mechanics of your loan is no longer just a detail; it is the most critical part of your purchase.
The Reality of 2026 Auto Loan Trends The current automotive market is defined by a tug-of-war between buyer intent and economic pressure.
Recent data shows that more than one in four new-car buyers are now opting for loan terms of 84 months or longer to keep monthly payments manageable. While this strategy lowers the immediate burden, it often leads to paying significantly more in interest over the life of the loan. Furthermore, with over 21% of financed purchases now carrying a monthly payment of $1,000 or more, the need for transparency and strategic planning has never been higher. 
Why Your Credit Score is Your Best Negotiating Tool Your credit score remains the primary lever in determining your interest rate.
As of Q2 2026, borrowers with 'super prime' credit scores enjoyed average rates near 4.41%, while those with poor credit faced rates exceeding 16%. Before you step into a dealership, check your credit report and use online calculators to understand what rates you qualify for. Remember, you are not obligated to use the dealer's financing. Securing a pre-approval from a credit union or your personal bank gives you a 'floor' rate, providing you with the leverage to ask the dealer to beat that offer. 

Navigating Dealer Incentives and 0% APR Deals Despite the broader economic climate, manufacturers are still deploying aggressive incentives to move inventory.
In October 2026, savvy shoppers can still find financing deals under 3% or even 0% APR on select models like the 2026 Acura Integra or various SUV lineups. When you see these offers, verify if they are stackable with other incentives, such as bonus cash or loyalty rebates. Always read the fine print—sometimes a 0% APR offer requires you to forgo a significant cash-back discount, and you must calculate which option saves you more money over the long term. 

The Hidden Costs of Stretching Your Loan Term It is tempting to stretch a loan to 72 or 84 months to lower your monthly payment, but this is a dangerous game.
A longer term means you are paying interest for a longer period, and you risk becoming 'underwater' on your loan—where you owe more than the car is worth—much faster. If you must choose a longer term to fit your budget, prioritize vehicles with high residual values, such as the 2026 Toyota RAV4 or the 2026 Honda CR-V, which tend to hold their value better than average, providing a safety net should you need to trade in early. 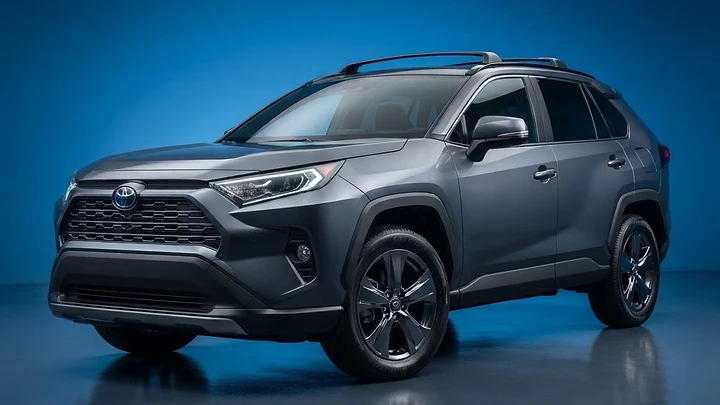

Frequently Asked Questions
Should I tell the dealer my pre-approved loan amount?
No. Negotiate the 'out-the-door' price of the vehicle first. Only after you have agreed on the final price should you discuss financing. Revealing your pre-approval limit early can lead dealers to manipulate the numbers to hit that maximum. #
Is it better to lease or buy in 2026?
Leasing typically offers lower monthly payments but no equity. If you prioritize lower monthly costs and want a new car every three years, leasing is viable. If you plan to keep the car for 5-10 years, buying is almost always the smarter financial move. #
What is the 'out-the-door' price?
This is the total cost of the vehicle, including taxes, registration, documentation fees, and any dealer-added accessories. Always ask for the 'out-the-door' price in writing before agreeing to any financing terms. #
Can I refinance my car loan later?
Yes. If you are forced to take a high-interest loan due to current market conditions, you can refinance your loan with a credit union or bank once interest rates drop or your credit score improves.
The Bottom Line The 2026 car market rewards the prepared.
Do not let the pressure of the showroom floor dictate your financial future. By securing your own financing, focusing on the total out-the-door price rather than just the monthly payment, and choosing reliable vehicles that hold their value, you can protect your investment and enjoy the open road with peace of mind.
The cars in this story
The real price and honest verdict on each one
- 2026 Toyota RAV4Compact SUV · from $31,900
- 2026 Acura IntegraSedan · from $33,400
- 2026 Honda CR-VCompact SUV · from $30,920
More car news

Best Time to Trade In a Car: The 2026 Honest Buyer’s Guide
Wondering when to trade in your car? Discover the optimal timing, market trends, and financial strategies to maximize your vehicle's value in 2026.

Smart Car Buying: Navigating the 2026 Market With Confidence
Master the 2026 car buying market with our honest guide. Learn how to secure financing, avoid hidden fees, and find the right vehicle for your budget today.

Paint Protection Film: Is PPF Worth It in 2026?
Considering paint protection film for your new 2026 vehicle? We break down the costs, benefits, and whether PPF is truly worth the investment for your car.